Business Insurance Online :: News
SHARE

Share this news item!

What IAG’s Modular Shelter Move Means for SMEs

Extreme weather is turning continuity planning into an insurance priority

What IAG’s Modular Shelter Move Means for SMEs?w=400

The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.

IAG’s latest investment through Firemark Ventures is a useful signal for Australian business owners: disaster recovery is no longer just about paying claims after the event.
It is increasingly about helping people and enterprises stay operational, connected and on-site while rebuilding happens around them.

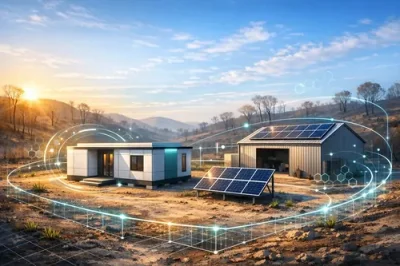
The insurer has taken a stake in Spacecube, a Melbourne-based maker of modular structures designed for rapid deployment after fires, floods and other major disruptions. The model was tested in regional Victoria after the January 2026 bushfires, where temporary units helped affected families remain on their properties during the rebuilding process. For rural operators, that distinction matters. A farm, workshop, accommodation business or regional service provider often cannot simply relocate without creating further financial and operational strain.

The practical appeal is clear. Spacecube structures can be delivered flat-packed, installed quickly and used on properties where normal services or access may be compromised. They can operate with solar and battery systems and connect with existing water and septic infrastructure. For insurers, that may reduce pressure on temporary accommodation claims. For business owners, it may help preserve continuity, customer relationships, livestock management, equipment supervision and community connection.

The broader issue for SMEs is the widening gap between risk awareness and practical preparation. IAG’s Resilient Futures Report, released in June 2026, found that 48% of surveyed small and medium-sized enterprises had been affected by extreme weather in the previous 12 months. The same research pointed to ongoing weaknesses in continuity planning and insurance reviews. That combination can quickly lead to underinsurance, especially where rebuilding costs, replacement equipment values and lost revenue assumptions have not been updated.

For business owners, the lesson is not to wait for a renewal notice before asking whether cover still reflects current conditions. Property sums insured, stock levels, portable equipment, business interruption periods, supplier dependencies and disaster recovery arrangements should all be checked regularly. Businesses in bushfire, flood, cyclone or storm-prone areas may also need to consider whether their policy assumptions match how long repairs, approvals, materials and labour could realistically take after a widespread event.

This is also where advice can be valuable. SMEs with complex premises, regional exposures or mixed personal and commercial assets may benefit from speaking with insurance specialists before an incident, not only after a claim has begun. It may also be timely to compare business insurance options and test whether existing cover still suits the way the business actually operates.

IAG’s Spacecube move is not a replacement for strong insurance settings. Rather, it highlights a shift in the market: resilience, recovery speed and continuity are becoming central to how business insurance value is judged.

Published:Wednesday, 1st Jul 2026
Author: Paige Estritori

Please Note: We do not endorse any specific products or companies. Some content is sourced from third parties, including press releases, and may not be independently verified for accuracy or completeness.

Share this news item:

Rate this article

0 Comments

No comments yet. Be the first to share your thoughts.

Insurance News

Broker Code Overhaul Puts Renewals and Disclosure in Focus
28 Oct 2026: Paige Estritori
A new Insurance Brokers Code of Practice has been launched by the National Insurance Brokers Association, putting clearer disclosure, renewal contact and client support standards on the agenda for Australian businesses that use brokers to arrange cover. The 2027 Code takes effect on 1 January 2027 and is designed to set out, in plainer language, what clients should be able to expect from subscribing insurance brokers. - read more
Workers Compensation Reform Puts Employer Cover Back in Focus
16 Sep 2026: Paige Estritori
Renewed debate around proposed changes to the NSW workers compensation system is a timely reminder that employee injury cover is not a set-and-forget obligation for business owners. While the details of reform are still being scrutinised by government, regulators, unions, employers and insurers, the underlying issue is clear: claims costs, psychological injury trends and scheme sustainability are placing pressure on how workplace injury risk is funded and managed. - read more
Cyber Underinsurance Is Becoming a Bigger SME Risk
09 Sep 2026: Paige Estritori
Fresh industry attention on cyber underinsurance is a timely reminder that many Australian small and medium businesses are still treating digital risk as an IT problem rather than a balance sheet risk. As more trading, payments, customer records, bookings and supplier relationships move online, a cyber incident can quickly become a cash flow, legal, operational and reputational event. - read more
Disaster Resilience Debate Puts SME Cover Back in Focus
02 Sep 2026: Paige Estritori
Fresh industry attention on disaster resilience is a timely reminder that Australian small and medium businesses cannot treat severe weather as an occasional inconvenience. The message emerging from the insurance sector is increasingly consistent: premiums, availability of cover and claims outcomes are being shaped not only by what a business owns, but by where it operates, how exposed it is, and what practical risk controls are in place. - read more
Why lithium-ion batteries are now a business insurance issue
26 Aug 2026: Paige Estritori
Lithium-ion batteries are moving from a workplace convenience to a serious insurance consideration for Australian small and medium businesses. As more businesses rely on rechargeable tools, e-bikes, scooters, point-of-sale devices, backup power units and portable electronics, insurers are paying closer attention to how those items are stored, charged and managed. - read more


Business Insurance Articles

Cybersecurity Risk Assessment: An Essential Guide for Business Owners
In today's digital age, cybersecurity has become a critical concern for businesses of all sizes. The increasing reliance on technology means that cyber threats are more prevalent than ever, making it essential for business owners to understand and manage these risks. - read more
How to Assess Business Insurance Needs for Different Occupations
Different occupations face different business risks. This guide explains how Australian sole traders, contractors, consultants, retailers, trades and other small business owners can assess which types of business insurance may be relevant to their activities. - read more
The Top 5 Insurance Policies Every Australian Start-up Needs
When embarking on the entrepreneurial journey of a start-up, it's imperative to safeguard the nascent enterprise with a reliable insurance safety net. Insurance acts as a vital shield, protecting the hard work and innovation of new businesses against unforeseen events and liabilities which can arise in the unpredictable world of start-ups. - read more
Assessing the Insurance needs of your Australian Labour Hire firm
As a labour hire firm, it is important to assess your insurance needs to protect your business from the risks it faces. Assessing your insurance needs involves identifying potential risks specific to your industry and taking steps to mitigate them. With the right coverage, you can protect your employees, clients, and business assets from unforeseeable circumstances, which could otherwise result in costly lawsuits or accidents. - read more
How to Choose the Right Insurance for Your Australian Retail Business
Running a retail business can be a risky endeavor. While you can minimize some of those risks with careful planning and management, you cannot eliminate them entirely. This is where insurance comes in. Having the right kind and amount of insurance coverage can make all the difference in protecting your business from financial loss, should the unthinkable happen. - read more

Knowledgebase
Insurance Deductible:
the amount that an insured is required to contribute toward an insurance claim as stipulated in an insurance policy. Otherwise known as the "policy excess".